MC_FED_09_26
by Generali Investments
Generali Asset Management | Market Commentary Your Partner for Progress. MARKET COMMENTARY
The Fed deliver s a clear hawkish message and bets on sustained growth Paolo Zanghieri September 16, 202 6
• The Fed has turned decisively more hawkish, raising rates and signalling one further hike this year as persistent inflation and broader commodity -price spillovers outweigh concerns about the growth outlook , which is proving extremely resilient . • In a much more informative press conference Warsh framed the move as the result of a months -long data-de- pendent process, rather than a reaction to market -pressures . Financial conditions are clearly not restrictive . • We expect no further moves in 2027: risks remain tilted towards tighter policy, but the four hikes priced by markets through next year appear excessive given the likely drag of sticky inflation on real incomes and con- sumption.
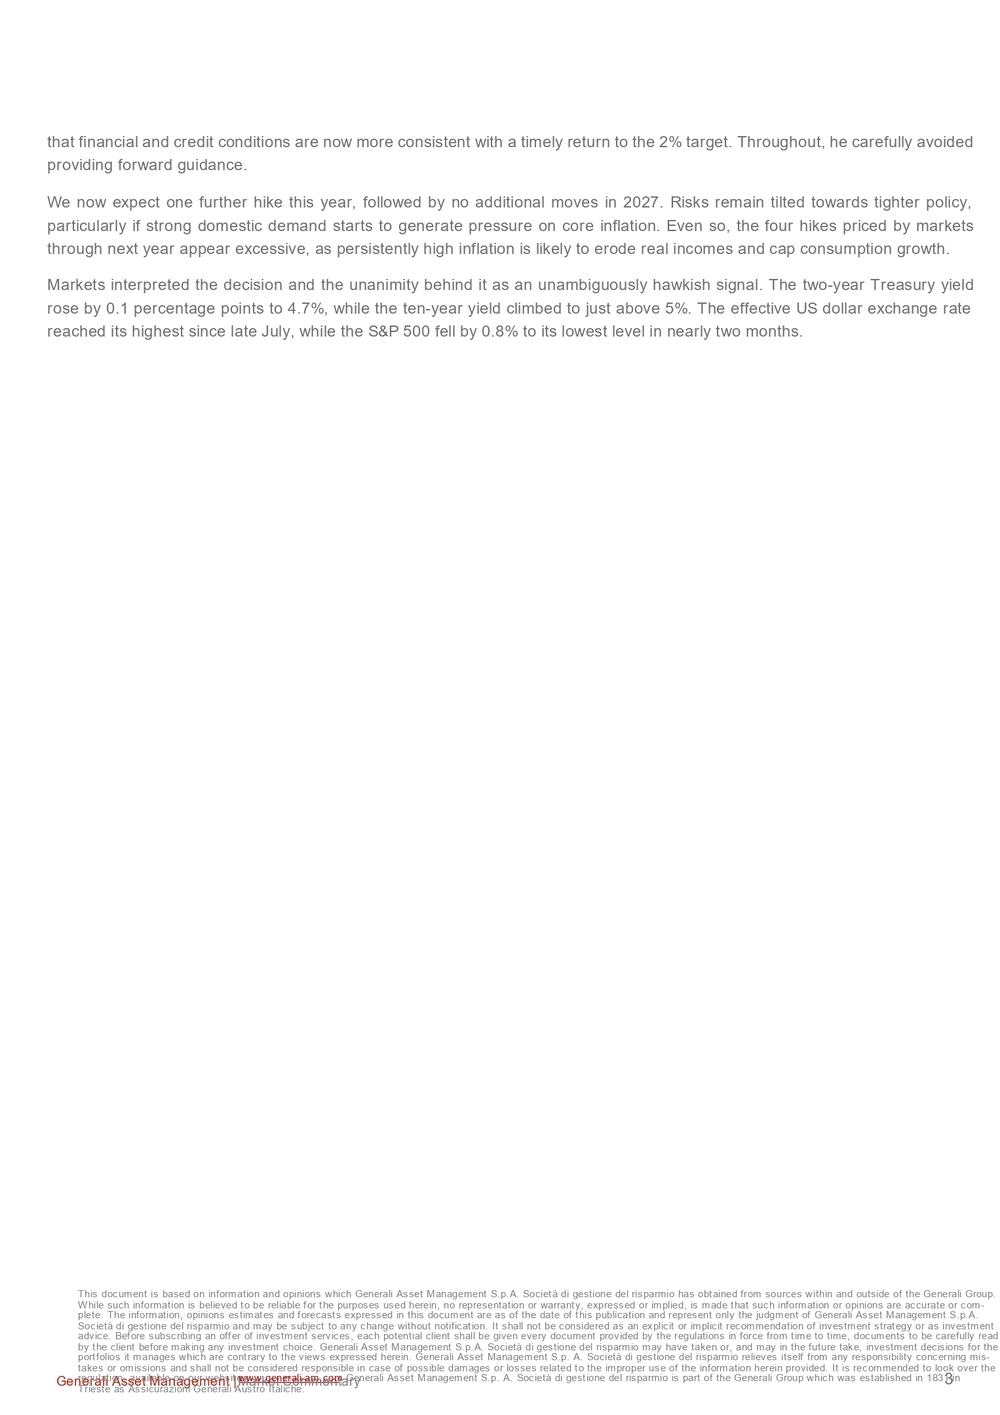
The Fed delivered a forceful hawkish shift, raising rates to 3.75% –4%, as e xpected, and signalling another hike by year-end after taking time to assess the economic outlook. The heavily revised statement presented a more bullish view of the economy and, impli citly, its capacity to withstand tighter monetary policy. Crucially, the Fed now seeks a “timelier return” of inflation to target, providing the rationale for the two hikes.
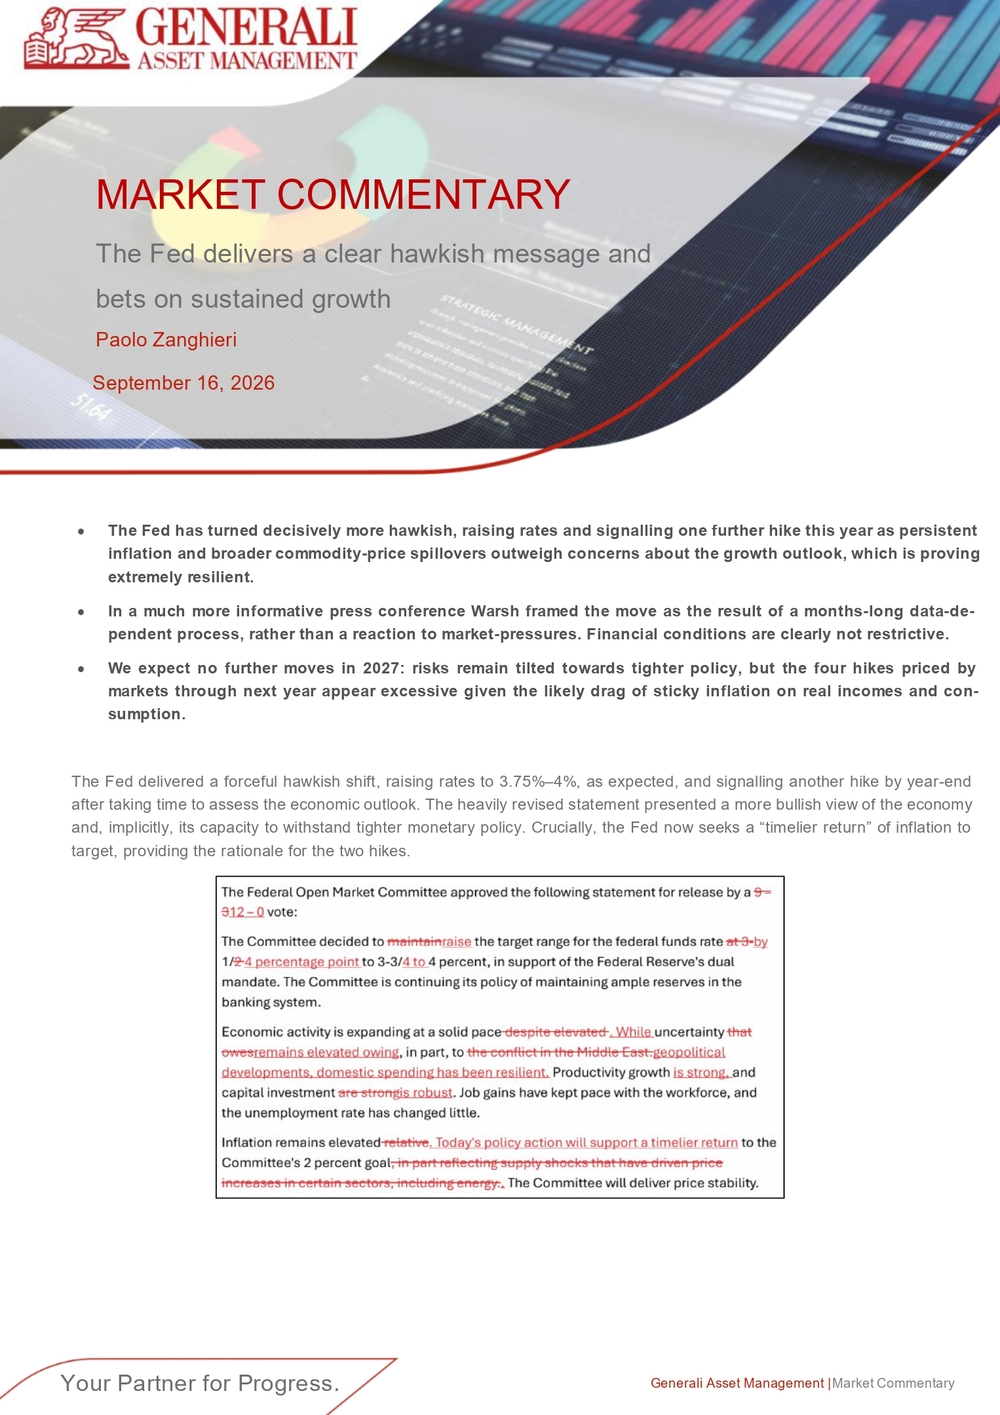
2 Generali Asset Management | Market Commentary The decision was unanimous among the 12 voting membe rs, while 12 of the 16 participants who submitted projections fa- voured two hikes this year (Warsh did not submit its projections) . This degree of agreement is notable after the dissenting comments heard in recent weeks . Adding to hawkish ness , eight FOM C participants would favour another hike in 2027 .
The new projections reinforce the Fed’s bullish assessment of the economy: growth was revised up this year and next, while unemployment remains at a low 4.1% throughout the forecast horizon. This year’s inflation projections were marked to market , but they still suggest that inflation will not return to target particularly quickly. The two rate hikes delivered this year are projected to be unwound gradually in 2028 and 2029, while the longer -run policy rate was nudged up by 0.1 percentage points to 3.2%, consistent with the more optimistic productivity outlook .
Warsh used the press conference to reinforce the FOMC’s confidence in the economy , providing many more details than in the past two meetings . He argued that demand continues to grow at a healthy pace despite elevated global uncertainty and that stronger productivity has raised the economy’s trend growth rate. With unemployment claims consistent with full employment and labour -market risks balanced , he sees limited economic damage from higher policy rates . Persistently high inflation —and evidence of broader spillovers from commodity prices —was the central reason for the hike. The latest data have disappointed: headline PCE inflation is estimated to have reach ed 3.6% in Aug ust, with the core rate at 3.2%. Warsh noted that commodities account for much of the headline increase . Although the Fed cannot influence individual prices, it can prevent relative -price increases from spreading through the economy via second -round effects. He highlighted signs that higher commodity prices are already spilling over into some goods categories , with the rapid rise in diesel prices as a case in point . Warsh presented the hike as the result of a deliberate, data -dependent process rather than a response to market pressure. In June, the committee reaffirmed its focus on core PCE inflation and the 2% target . In July, it reviewed the new information and judged that waiting another seven weeks for additional evidence was worthwhile , and in September it eventually acted . The FOMC ultimately concluded that financial conditions were barely restrictive and decided to withdraw some accommodation . Warsh argued
3 Generali Asset Management | Market Commentary that financial and credit conditions are now more consistent with a timely return to the 2% target . Throughout, he carefully avoided providing forward guidance. We now expect one further hike this year, followed by no additional moves in 2027. Risks remain tilted towards tighter policy, particularly if strong domestic demand starts to generate pressure on core inflation . Even so , the four hikes priced by markets through next year appear excessive , as persistently high inflation is likely to erode real incomes and cap consumption growth. Markets interpreted the decision and the unanimity behind it as an unambiguously hawkish signal. The two -year Treasury yield rose by 0. 1 percentage points to 4.7%, while the ten -year yield climbed to just above 5%. The effective US dollar exchange rate reached its highest since late July , while the S&P 500 fell by 0.8% to its lowest level in nearly two mo nths.
This document is based on information and opinions which Generali Asset Management S.p.A. Società di gestione del risparmio h as obtained from sources within and outside of the Generali Group. While such information is believed to be reliable for the purpos es used herein, no representation or warranty, expressed or implied, is made that such information or opinions are accurate o r com- plete. The information, opinions estimates and forecasts expressed in this document are as of the date of this publication an d represent only the judgment of Generali Asset Management S.p.A. Società di gestione del risparmio and may be subject to any change without notification. It shall not be considered as an exp licit or implicit recommendation of investment strategy or as inve stment advice. Before subscribing an offer of investment services, each potential client shall be given every document provided by t he regulations in force from time to time, documents to be carefully read by the client before making any investment choice. Generali Asset Management S.p.A. Società di gestione del risparmio may have taken or, and may in the future take, investment decisions for the portfolios it manages which are contrary to the views expressed herein. Generali Asset Management S.p. A. Societ à di gestione del risparmio relieves itself from any responsibility concerning mis- takes or omissions and shall not be considered responsible in case of possible damages or losses related to the improper use of the information herein provided. It is recomme nded to look over the regulation, available on our website www.generali -am.com . Generali Asset Management S.p. A. Società di gestione del risparmio is part of the Generali Group which was established in 1831 in Trieste as Assicurazioni Generali Austro Italiche.